Your Best Investment May Be a Tax Strategy
Investors spend enormous energy trying to beat the market. That effort can be pointless if taxes consume the extra return before it can compound.
A better first investment may be learning the tax code and building a tax strategy: capture an employer match, use available retirement accounts, choose between traditional and Roth contributions thoughtfully, use an HSA when eligible, and keep tax-inefficient assets out of taxable accounts when practical.
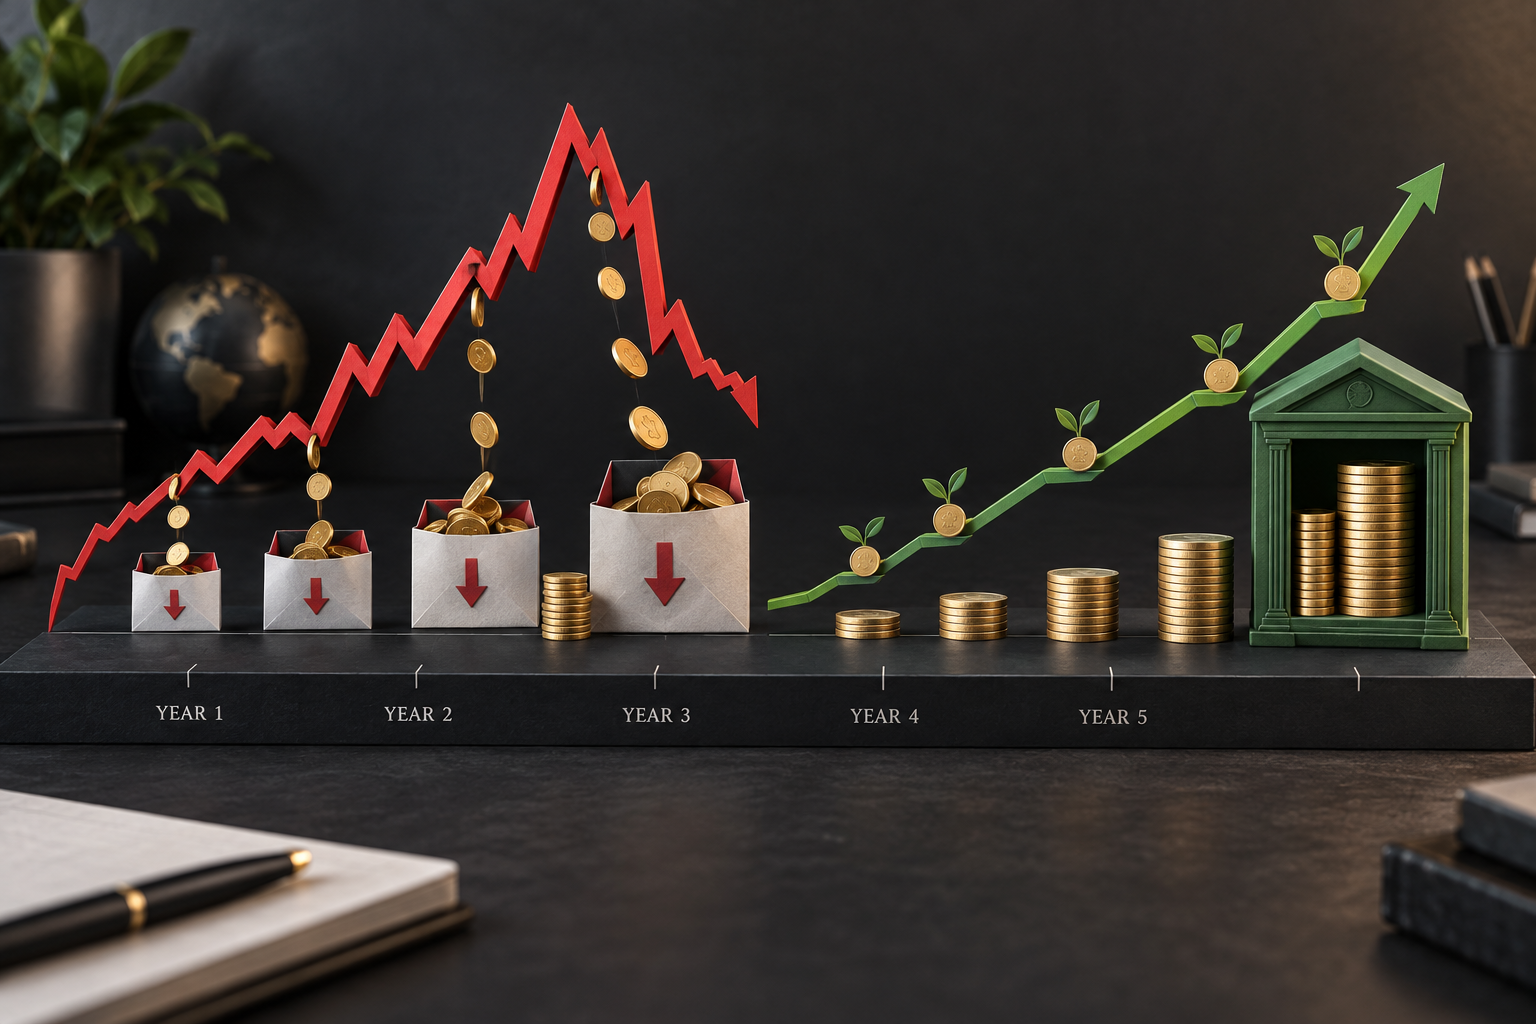
A five-year example
Assume two people can direct $20,000 of gross income per year toward investing. Contributions happen at year-end, there is no employer match, and the tax rates are simplified for illustration.
| Beats the index | Tax-aware index investor | |
|---|---|---|
| Gross annual return | 11% | 8% |
| Account | Taxable brokerage | Traditional retirement account |
| Annual amount invested | $14,000 after 30% income tax | $20,000 before income tax |
| Return after annual tax drag | 7.7% | 8% tax-deferred |
| Balance after five years | $81,643 | $117,332 before withdrawal tax |
| After hypothetical 22% retirement tax | $81,643 | $91,519 |
The first investor picked the better-performing portfolio and still finished about $9,900 behind. The second investor did not beat the index. They simply gave more money more time to compound before paying tax.
The point
Returns matter, but after-tax returns are what you keep. Before searching for the next winning investment, learn which accounts are available to you and decide where each investment belongs. A good tax strategy can be more reliable than trying to outsmart the market every year.
Traditional retirement contributions and earnings are generally tax-deferred, not tax-free; withdrawals are generally taxable, and early distributions may face additional tax. Start with the IRS overview of retirement plans, then confirm your strategy with a qualified tax professional.
This simplified example is educational, not individualized tax or investment advice. Actual results depend on account eligibility, contribution limits, tax rates, turnover, fees, withdrawal timing, and future law.